Bank Deposits: Behind the 39 Billion Guarantee, the Question of Your Protection
Reinforcing Financial Foundations: The Collective Fund for Deposit Guarantees and Customer Concerns
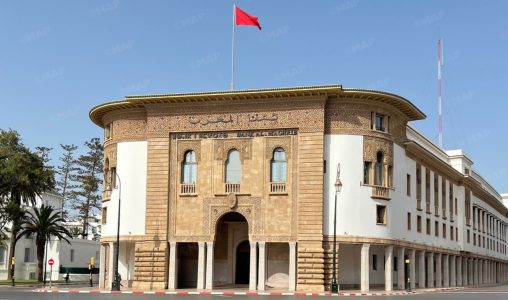
The Collective Fund for Deposit Guarantees boasts a stronger financial foundation. However, for bank customers, the pressing questions revolve around how much of their money is protected and how they could access it. Bank Al-Maghrib is currently focusing on modernizing the resolution framework to address these issues.
Individuals often have various financial goals in mind—be it saving to purchase an apartment, funding a child’s education, or simply making ends meet until the end of the month. On a bank statement, all the numbers may appear similar, but for households, these funds represent a vital safety net. It is within this perspective that the figures from the Collective Fund for Deposit Guarantees should be understood. As of the end of 2025, its capital and equivalent resources stand at 39 billion dirhams, reflecting an increase of 8.1%. This cushion accounts for more than 3% of eligible deposits, with compensation capped at 80,000 dirhams per depositor.
While this amount is reassuring, it does not clarify whether the fund’s resources would be sufficient in the event of a systemic shock. On this note, one particular project deserves more attention. In its 2025 banking supervision report, Bank Al-Maghrib mentions ongoing work in partnership with the European Bank for Reconstruction and Development (EBRD) to review the compensation cap and assess the fund’s sizing. These efforts are preliminary and do not imply the announcement of a new guarantee already in effect.
A High Number of Small Depositors
Data from the Collective Fund for Deposit Guarantees reveals two stark realities. Among individual depositors, 92% have less than 80,000 dirhams and hold only 14% of eligible deposits. In contrast, 4% possess more than 200,000 dirhams and account for 71% of the total funds. This significant disparity illustrates the complex judgment the regulator faces: should the priority be to provide social protection to the highest number of clients, or should the focus be on ensuring adequate coverage of the capital base to maintain financial stability? Raising the compensation cap necessitates defining the parameters of this coverage while also identifying the necessary bank contributions to fund it.
Cash Remains Predominant
The modernization of the resolution framework comes amid a monetary landscape where cash transactions remain predominant. In 2025, cash withdrawals represented 85% of card transactions. It would be misleading to interpret this alone as a sign of distrust in banks. Nevertheless, the prevalence of cash withdrawals prompts an important question: what do customers know about the protection mechanisms in place for the money they leave in their accounts?
Lessons from American Bank Failures
On the international stage, the collapse of Silicon Valley Bank in March 2023 highlighted the importance of understanding deposit composition. Approximately 90% of the deposits at this American bank were uninsured. In less than 24 hours, customers withdrew or attempted to withdraw nearly all their deposits, according to the Federal Deposit Insurance Corporation (FDIC).
This incident adds a new dimension to the IT project referenced by the Collective Fund for Deposit Guarantees: identifying beneficiaries, calculating their entitlements, and preparing for disbursements is more than a simple administrative task.
Preparing Without Raising Alarm Bells
Morocco has also tested its ability to manage a cross-border crisis through a simulation conducted in February 2025 with several regional authorities. In its report, Bank Al-Maghrib simultaneously presents a reform of the framework for handling banking difficulties aimed at preserving essential services while limiting reliance on public funds.
These preparations do not signal a diagnosis of fragility. The average capital adequacy and liquidity ratios of conventional banks remained above the regulatory minima as of the end of 2025. Nonetheless, they raise a pertinent issue for every user: beyond the amount accumulated by the fund, what level of protection will actually be accessible on the day it’s needed?