PLF 2027: The Executive Seeks to Extend Income Tax Exemption to Salaries Below 10,000 DH
Fiscal Reform Proposal: Exemption from Income Tax on Salaries Below 10,000 Dirhams Starting January 2027
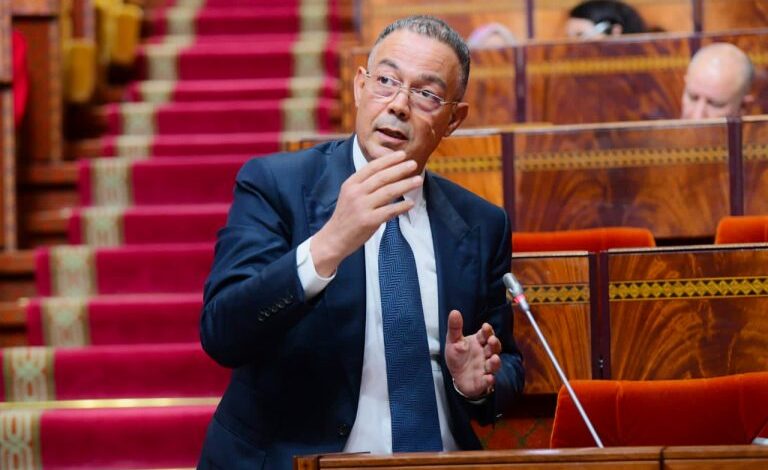
Presented by Fouzi Lekjaa on October 23, the fiscal reform aims to exempt monthly net salaries under 10,000 dirhams from income tax starting in January 2027. Estimated to cost 5.5 billion dirhams in its first year, this measure is part of a gradual overhaul of the tax brackets extending until 2031. It is designed to enhance purchasing power, although its impact will depend on the final adoption of the proposed legislation.
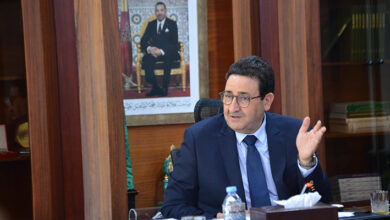
The message is clear, but the financial implications are significant. As part of the 2027 Finance Bill, the government is proposing a new tax relief for salaried individuals: net monthly earnings below 10,000 dirhams would be exempt from income tax starting January 1, 2027. While presenting the budgetary orientations before both Chambers of Parliament, Minister of Economy, Finance and Public Performance, Fouzi Lekjaa, indicated that approximately 87% of employees would be completely exempt from income tax.
This announcement carries a dual significance. On one hand, it aims to increase disposable income for households, and on the other, it seeks to gradually revise the structure of labor income taxation. For the government, the reform is a means of supporting purchasing power in a context where the cost of living remains a primary concern for households.
A Budgetary Effort of 5.5 Billion Dirhams
The proposed system plans to raise the threshold for the first tax bracket from 40,000 to 60,000 dirhams annually for tax-exempt income. It also entails restructuring the tax brackets and progressively lowering rates, with the goal of reducing the top marginal rate from 37% to 30% by 2031.
According to the estimates presented by the minister, the majority of affected employees could see a monthly gain of around 500 dirhams starting in 2027. The budgetary impact of this initial phase is estimated at 5.5 billion dirhams.
This figure reflects the commitment from public finances. It also highlights the delicate balance the government faces: reducing tax pressure on labor income without jeopardizing budgetary stability, all while public policy financing needs remain significant.
However, the actual benefit will vary depending on each taxpayer’s taxable income and fiscal situation. Thus, the announced relief should not be interpreted as a uniform increase of 500 dirhams for all employees.
A Reform Extended Until 2031
The changes extend beyond the exemption threshold. The Finance Bill outlines a gradual transition of tax rates and brackets between 2027 and 2031, evolving these parameters over the years. This trajectory aims to sustainably alter the distribution of the tax burden among different income categories.
The chosen timeline allows the state to spread the budgetary effort, but it also entails a cautious interpretation of the anticipated benefits in the medium term. The expected amounts in the coming years will depend on the implementation of successive tax brackets and the provisions that will ultimately be adopted.
For businesses, the reform will also require adjustments to payroll systems and withholding practices. The publication of the final text and its application guidelines will be crucial in translating the announcement into concrete changes in salary statements.
Purchasing Power Put to the Test
Exempting income tax represents a direct tool for supporting disposable income. Nevertheless, its economic effect cannot be assessed in isolation. The actual fiscal benefit will significantly depend on price developments, households’ fixed expenses, and wage dynamics.
The proposal also raises an equilibrium question: how to reconcile reduced labor taxation with the financing of public services and necessary investments for growth? The projected cost of 5.5 billion dirhams in 2027 underscores the importance of this balancing act.
For the government, the reform signifies a step towards restructuring income taxation. For employees, its value will materialize in the amount effectively retained each month. Balancing social ambitions with budgetary constraints, the timing of implementation and the actual effects on disposable income will be the key indicators to monitor.