Current Accounts, Savings Accounts: The True Cost of Idle Money
While banks report comfortable profits and Bank Al-Maghrib adjusts its monetary policy tools, another, quieter reality is unfolding in the bank statements of households. Hundreds of billions of dirhams continue to be stored in non-interest bearing current accounts or in savings instruments that struggle to generate real value.
For executives, professionals, and parts of the urban middle class, the absolute security of a current account increasingly resembles an expensive comfort. The money is certainly available, but it is not working for them. And once inflation is taken into account, it may even be gradually losing its substance.
### Billions in Slumber
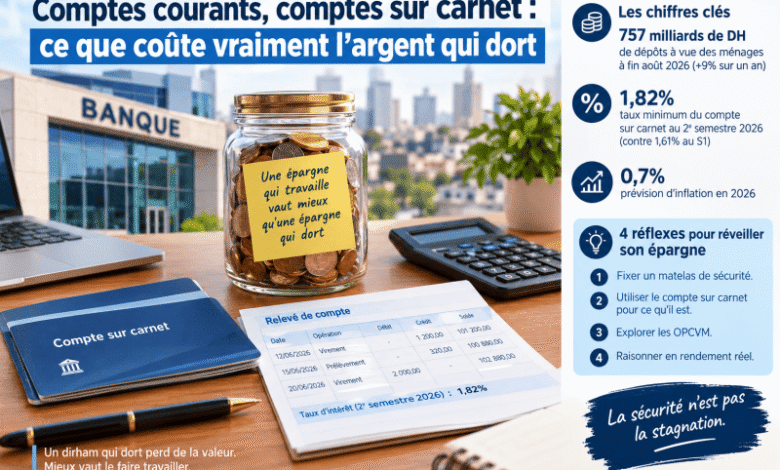
The monetary statistics from Bank Al-Maghrib confirm this reality. The liquidity reflex remains deeply ingrained. By the end of August 2026, household sight deposits with banks amounted to approximately 757 billion dirhams, a 9% increase year-on-year.
These amounts are immediately accessible and, in principle, generate no interest. Yet, they represent a valuable resource for credit institutions, providing stable, low-cost financing that enhances their balance sheets and supports their credit distribution activities.
This is where the paradox lies. The saver allows their money to be available to the bank, which, in turn, transforms it into financing capacity, intermediation margins, and ultimately, net banking products. Meanwhile, the customer generally perceives no interest in return.
### The Passbook Account: An Underperforming Safe Haven
The passbook account remains the primary refuge when savers move away from their current accounts. However, its official yield remains modest. For the second half of 2026, Bank Al-Maghrib set the minimum applicable rate for passbook accounts at 1.82%, up from 1.61% in the first half.
For 100,000 dirhams placed for a year, this generates approximately 1,200 dirhams net. While this is a tangible amount, it is limited in relation to a household’s financial objectives, such as accumulating a down payment for a home, funding education, preparing for retirement, or protecting against job-related uncertainties.
Inflation, for its part, remains contained, with forecasts suggesting around 0.7% for 2026 following a period of sensitive pricing in certain essential expenditures. After taxes and inflation, the real yield on the passbook account can be slightly positive on a national average. However, this is only valid if the inflation actually experienced by the household does not exceed this threshold.
Because the average figures mask individual situations. A household facing rising rent, healthcare costs, education fees, or transportation expenses does not live with the aggregated inflation published by the National Institute of Statistics; it lives with its own inflation.
### The Invisible Tax of Liquidity
Let’s consider a simple example. An executive has 200,000 dirhams in their current account, beyond any reasonable safety net. Every year, this amount produces nothing.
The current account serves a purpose: to pay, to receive, to cover daily expenses. It is not meant to be the default vault for wealth. When liquidity consistently exceeds operational needs, it stops being a form of prudence and becomes inertia.
The low return on liquid savings is not a technical inevitability; it also stems from a habit of considering the current account as an investment when it is not one.
Banks, for their part, have little incentive to consistently push their customers toward reallocating their funds. Cheap sight deposits improve their financing conditions. For savers, the question is not so much about abruptly exiting liquidity, but rather about prioritizing it. Part should remain immediately accessible, while the surplus can be directed toward solutions better suited to their financial horizon and risk appetite.
### Four Reflexes to Revitalize Savings
1. Establish a safety cushion.
2. Use the passbook account for its intended purpose.
3. Explore mutual investment funds (OPCVM).
4. Think in terms of real yield.
The essential message can be summed up in one sentence: security does not equate to stagnation. Retaining liquidity is a management decision. Leaving significant sums in a non-interest-bearing account year after year often indicates a lack of decision-making.
The challenge is not only to encourage households to save but also to teach them to differentiate between money that is meant to be spent, money that is meant for security, and money that is intended to work. Because an idle dirham is not neutral; it gradually and surely loses a part of its purchasing power.