Regional Integration: Can Morocco Truly Bypass the Dollar and the Euro?
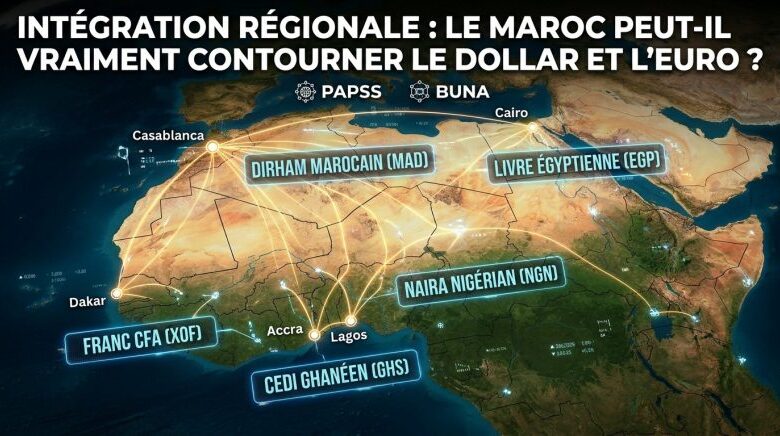
Morocco Joins the Race for Regional Financial Infrastructure
By joining the Pan-African Payment and Settlement System (PAPSS) and finalizing its membership in the Arab Buna platform, Bank Al-Maghrib has positioned Morocco in a discreet yet decisive competition in the realm of regional financial infrastructures. The stakes go beyond merely reducing banking fees; they involve monetary sovereignty, Casablanca’s role in African and Arab financial flows, and the Kingdom’s ability to lessen its dependence on payment systems dominated by third-party currencies.
Over a year ago (in June 2025), Bank Al-Maghrib officially signed its membership agreement with PAPSS, becoming the 17th country in this Pan-African network. The platform, developed by Afreximbank in collaboration with the Secretariat of the African Continental Free Trade Area (AfCFTA), aims to facilitate cross-border payments in local currencies with instantaneous transfers.
For Moroccan companies targeting West Africa, the Sahel, or East Africa, the implications are significant: reducing delays, limiting successive conversions, and securing payments that are often reliant on correspondent banks located outside the continent.
Bank Al-Maghrib has also completed its membership with Buna, the Arab system for the compensation and settlement of cross-border payments. The stated objective is similar—to facilitate the use of local currencies in trade between Arab countries.
The Dollar and Euro: Declining, But Not Disappearing
The PAPSS does not aim to replace the dollar and euro. Its ambition is more focused—turning African currencies into the standard medium for intra-African exchanges, where they have previously been systematically converted into third-party currencies.
Practically, a Moroccan importer can make a payment in dirhams, while their African supplier can receive naira, cedis, or CFA francs, depending on the available corridors. Commercial transactions are thus conducted in local currencies, with transfers that can be executed instantly.
However, the architecture maintains a compensatory step between national systems. Daily net settlements result in residual positions settled in a strong currency by Afreximbank. Therefore, the dollar and euro do not disappear; they recede from the level of commercial transactions to that of central interbank compensation.
This is precisely where the strategic challenge lies. Every dirham that can be directly settled against an African currency reduces reliance on correspondent banking circuits, lowers exchange costs, and shortens the settlement cycle. Morocco is not seeking to replace global reserve currencies; it aims to stop using them by default to pay its immediate economic neighbors.
The Real Gain: Cost and Time
Currently, a transaction between Morocco and several African markets may involve multiple conversions, correspondent fees, and longer settlement times. PAPSS promises a fast, traceable payment in local currency, accessible through banks and service providers connected to the network.
For an exporting SME, the difference can be significant. Shorter settlements reduce the need for operational financing. Direct conversions limit exchange costs. Enhanced traceability facilitates compliance with documentation.
However, the impact will depend on a decisive factor: the number of Moroccan banks that are genuinely connected to the system, the depth of available corridors, and the volume of bilateral exchanges. Membership by the central bank opens the door; it does not automatically create a liquid market.
Significant Barriers Remain
The first barrier is regulatory. The dirham is not fully convertible on the capital account, and currency exchange operations remain regulated by the Office des Changes. Any regional interconnection must thus reconcile the fluidity of commercial payments with the prevention of capital flight.
The second barrier is compliance. PAPSS imposes validation controls on payment instructions and establishes a compliance architecture among jurisdictions with heterogeneous AML/CFT frameworks. As the network expands, the harmonization of standards becomes critical.
The third barrier is financial. African currencies exhibit varying levels of liquidity, volatility, and exchange risk. Therefore, Moroccan banks will need to develop capabilities in hedging, position management, and knowledge of local counterparties.
Casablanca: Hub or Just a Node?
Morocco possesses significant advantages, including a structured financial center, banks operating in around twenty sub-Saharan African countries, a geographic position between the Atlantic, the Sahel, and Europe, and an actively engaged economic diplomacy oriented towards the continent.
However, mere membership in PAPSS and Buna does not suffice to make Casablanca a hub. It will require liquid corridors, operational commercial banks, robust foreign exchange infrastructures, and a regulatory framework capable of supporting flows without opening the door to speculative arbitrage.
The critical question remains: can Morocco become one of the most efficient transit points between Africa, the Arab world, and Europe while maintaining control over its monetary framework?
The Decoder